BJ’s Wholesale Club Holdings Delivers 16% Revenue Growth in Q2 2026 - Alphastreet
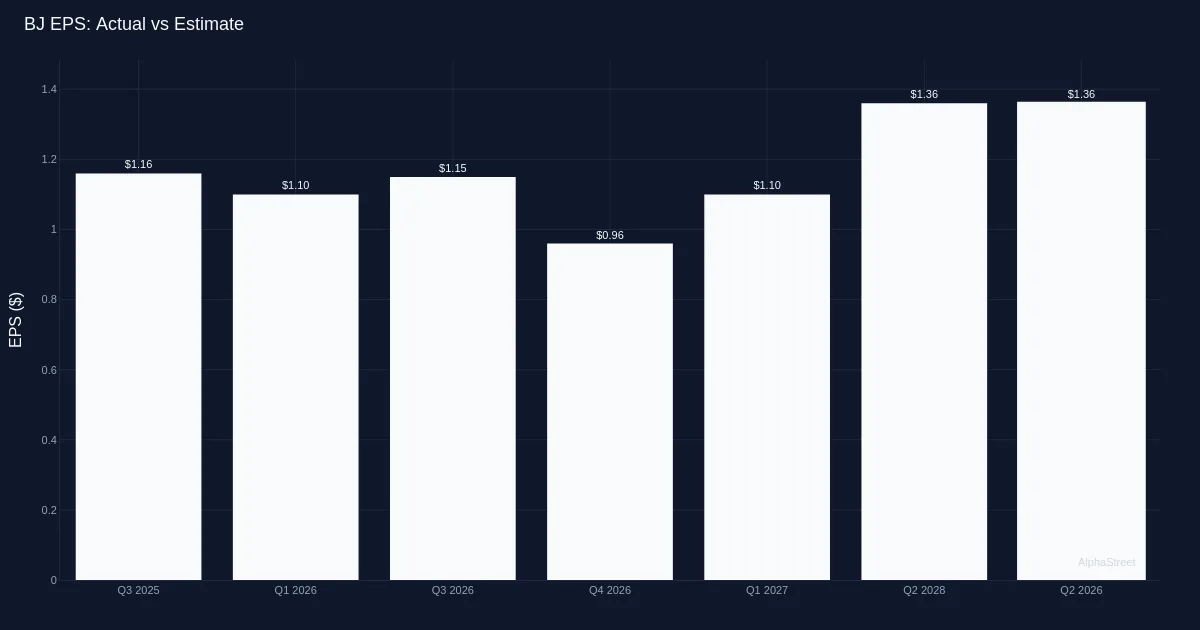
Solid beat powers shares. BJ's Wholesale Club Holdings, Inc. (NYSE:BJ) delivered Q2 2026 adjusted earnings of $1.36 per share on revenue of $5.38B, marking ...

BJ’s Wholesale Club Holdings Delivers 16% Revenue Growth in Q2 2026 - Alphastreet
BJ’s Wholesale Club Holdings, Inc. (NYSE: BJ) posted adjusted earnings of $1.36 per share for the second quarter of 2026, while revenue climbed to $6.2 billion. The company reported net profit of $173.9 million, indicating that the surge in sales translated into tangible earnings for shareholders. After the release, the stock moved only marginally, suggesting that investors had largely priced in the results amid an already solid year‑to‑date performance.
Revenue Acceleration Highlights Strength
Quarterly revenue rose 15.7% compared with the same period a year earlier, a gain the company attributes to genuine operational momentum rather than accounting tricks. Comparable club sales, which include gasoline, increased 11.9% on a like‑for‑like basis. Such double‑digit growth in a discount‑retail setting points to BJ’s capturing additional market share as shoppers continue to prioritize value. The improvement appears driven by higher foot traffic and larger basket sizes instead of temporary cost‑cutting measures.
Membership Model Fuels Traffic
The rise in comparable sales underscores the appeal of BJ’s warehouse format to price‑sensitive households navigating an uncertain economy. Gasoline sales contributed to the 11.9% comparable growth, highlighting the role of fuel stations in drawing members into the clubs more frequently. This increased visitation creates cross‑selling opportunities for fresh foods, general merchandise, and private‑label items, which typically deliver stronger margins for the retailer.
Analyst Sentiment Cautiously Positive
Wall Street analysts have issued nine buy ratings, thirteen hold ratings, and one sell rating on BJ’s stock. This mix reflects confidence in the company’s execution while signaling that many investors are waiting for confirmation that the momentum can be sustained. The predominance of hold recommendations suggests that the market views the current price as fairly valued, with upside contingent on the firm’s ability to maintain its competitive edge.
Market Reaction Remains Flat
The near‑flat movement in BJ’s share price after the earnings release indicates that investors either anticipated the numbers or are adopting a wait‑and‑see stance regarding future growth. In an environment where earnings beats often spark immediate rallies, the muted response may reveal concerns about the difficulty of achieving comparable growth in upcoming quarters or doubts about the durability of consumer spending within the discount channel.
Outlook for the Discount Retail Segment
BJ’s performance provides a snapshot of broader trends in the discount‑retail sector, where membership‑based models continue to attract cost‑conscious shoppers. The company’s ability to leverage fuel sales to boost overall club traffic could serve as a template for peers seeking similar advantages. As the macroeconomic backdrop evolves, analysts will monitor whether BJ’s can replicate its Q2 success in the later part of the year and beyond.
Investors should keep an eye on the firm’s upcoming guidance and any shifts in consumer behavior that could affect the sustainability of its growth trajectory.
Source: news.alphastreet.com · 2026-08-21