Donaldson Company Tops Q4 2026 Profit Forecast With $1.15 EPS - Alphastreet
Solid Beat. Donaldson Company, Inc. (NYSE:DCI) delivered Q4 2026 adjusted earnings of $1.15 per share, surpassing analysts' $1.06 forecast by 8.5%, while re...

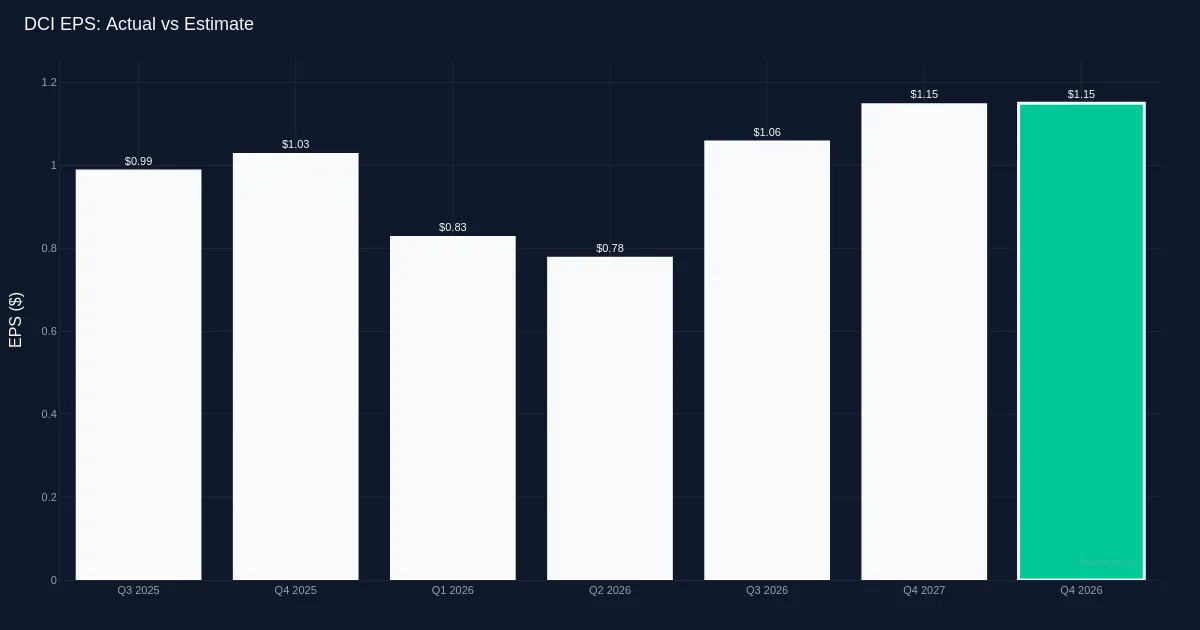
Donaldson Company, Inc. posted adjusted earnings of $1.15 per share for the fourth quarter of 2026, beating the consensus estimate of $1.06 by 8.5%. Revenue for the period reached $1.06 billion, surpassing the $983.4 million forecast by 7.7%. Net income totaled $136.0 million, showing balanced strength on both the top and bottom lines. The stock moved only marginally after the release, indicating investors may be weighing the quality of the beat and looking for more clarity on the demand environment.
Revenue‑driven Momentum
The outperformance stemmed mainly from higher‑than‑expected sales rather than aggressive cost cuts. Quarterly revenue rose 8.0% from $980.7 million recorded in the same quarter a year earlier, suggesting Donaldson is either gaining market share or benefiting from favorable conditions in the filtration market. Mobile Solutions generated $634.9 million, up 7.9% year over year, underscoring resilience in the core segment that supplies engine and equipment manufacturers. The recent Facet acquisition added $30 to quarterly revenue, providing a modest boost beyond organic growth.
Measured Guidance Outlook
Company executives projected adjusted earnings for fiscal 2027 in a range of $4.22 to $4.38 per share. This guidance reflects confidence in the visibility of industrial end markets and the firm’s filtration technology strategy. With the quarter’s solid performance and $136.0 million in net income indicating operational leverage, Donaldson appears positioned to meet—or possibly exceed—the lower end of the outlook, provided macroeconomic conditions remain stable.
Market Reaction and Analyst Sentiment
Even with the earnings and revenue beats, the share price stayed essentially flat. The muted reaction may signal that investors had already priced in a beat, are cautious about the durability of growth rates in industrial markets, or are questioning future margin trends. The 8.5% earnings beat and 7.7% revenue beat are notable, yet the lack of price movement suggests either heightened expectations or a careful stance toward the broader industrial machinery sector. Wall Street’s consensus rating stands at two buys, seven holds and no sells, indicating a largely neutral view of the stock. The predominance of hold recommendations implies analysts consider Donaldson fairly valued at current levels, even after a quarter that outperformed expectations on several fronts. The absence of sell ratings offers a baseline of confidence, while the limited number of buy ratings suggests analysts may await clearer evidence of sustained margin expansion or accelerating organic growth before upgrading their stance.
Investor Outlook
Overall, Donaldson’s fourth‑quarter results demonstrate solid top‑line momentum and healthy profitability, but the market’s subdued response highlights lingering uncertainty about the sector’s longer‑term trajectory. Investors will likely monitor upcoming quarterly reports for signs of continued revenue growth, margin improvement and the company’s ability to navigate any macroeconomic headwinds that could affect industrial demand. This coverage is for informational purposes only and does not constitute investment advice.
Source: news.alphastreet.com · 2026-08-26