J. M. Smucker Tops Q1 2027 Profit Forecast With $3.24 EPS - Alphastreet

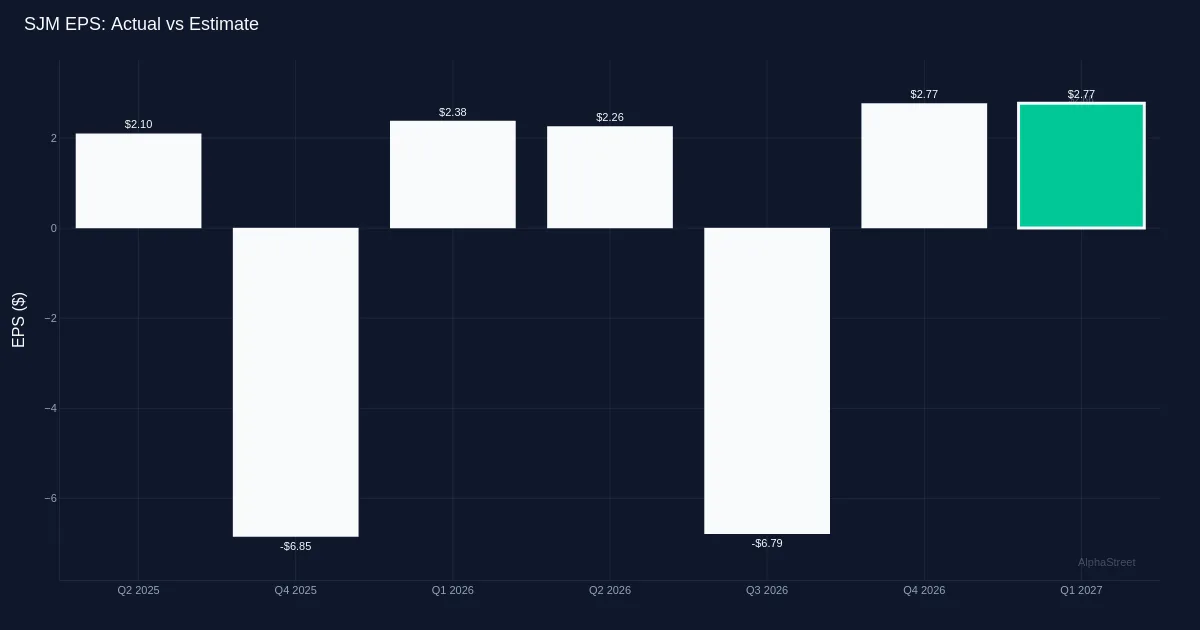
J. M. Smucker Beats Q1 2027 Profit Forecast, Revenue Slightly Low
The J. M. Smucker Company posted adjusted earnings of $3.24 per share for the first quarter of 2027, surpassing the Wall Street consensus of $2.66 by 21.8%. Adjusted net income for the period was $346.5 million. Revenue reached $2.21 billion, falling short of the $2.28 billion analysts had expected, a miss of roughly 3%. The stock gained 3.9 percent in midday trading on Wednesday.
Pricing Discipline Fuels Earnings
Management credited the earnings beat largely to disciplined pricing rather than a surge in unit sales. Net price realization added four percentage points to the quarter’s results, allowing revenue to climb 5.0 percent year‑over‑year from $2.11 billion in Q1 2026. The modest revenue shortfall suggests that volume growth or product mix may have faced some pressure, but the company’s ability to lift prices without eroding demand highlights a careful balance in an inflation‑sensitive market.
Coffee Segment Leads Growth
The U.S. Retail Coffee business emerged as the most dynamic part of Smucker’s portfolio, delivering $807.8 million in sales and expanding 13.0 percent from the same quarter a year earlier. This double‑digit increase outpaced the company’s overall 5.0 percent revenue rise, underscoring coffee’s role as a key growth engine. The strong performance likely reflects both effective price actions and favorable trends within the broader coffee category.
Outlook for the Full Year
For the 2027 fiscal year, management projected adjusted earnings per share in a range of $10.50 to $11.00. The midpoint of $10.75 signals a notable lift from the first‑quarter run rate, implying either accelerating momentum in later quarters or the impact of typical seasonal patterns. Executives expressed confidence that pricing discipline can be sustained even as commodity costs remain volatile and competition intensifies across the packaged‑foods landscape.
Analyst Sentiment Remains Even
Wall Street analysts are split evenly on Smucker, with nine buy recommendations and nine holds, and no sell ratings recorded. The balanced view reflects the company’s reputation as a steady operator with well‑known brands, while also acknowledging the sector’s ongoing challenges such as shifting consumer tastes and the rise of private‑label alternatives.
Source: news.alphastreet.com · 2026-08-26