UiPath Posts 13% Revenue Jump in Q2 2027, Misses on EPS - Alphastreet
Mixed Quarter. UiPath, Inc. (NYSE:PATH) delivered a revenue beat but missed on the bottom line in Q2 2027, posting non-GAAP EPS of $0.15 against the $0.16 c...

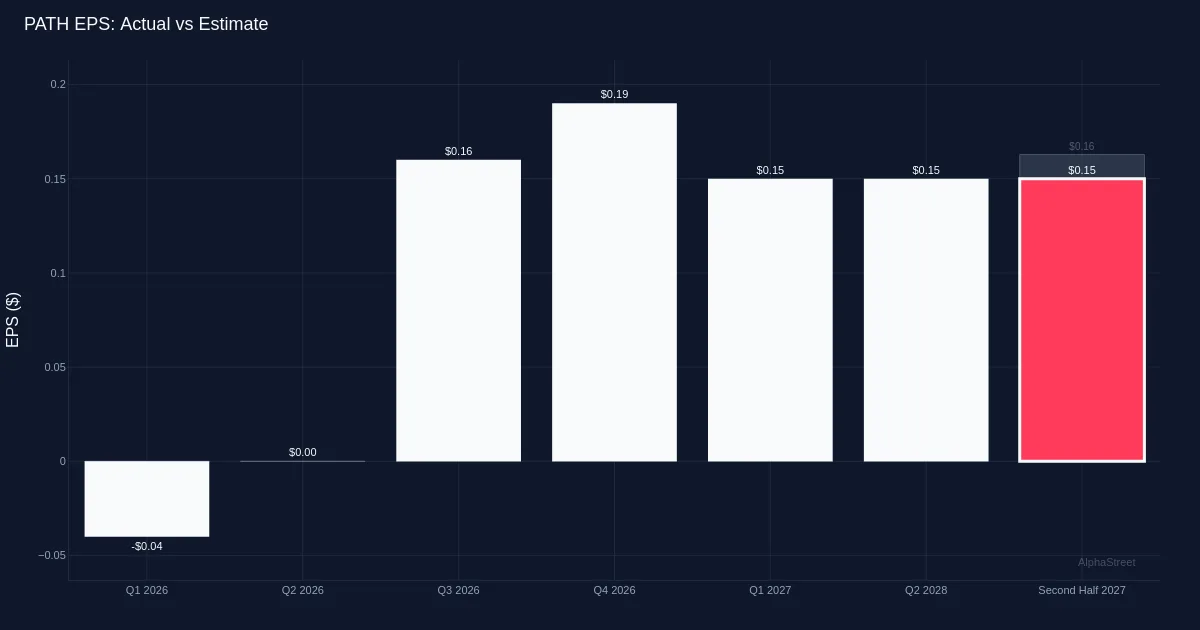
UiPath Reports 13% Revenue Growth in Q2 2027, Falls Short on EPS
UiPath, Inc. (NYSE: PATH) announced its Q2 2027 financial results, which showed a mixed performance. The company reported a revenue beat, but missed on the bottom line. UiPath's non‑GAAP EPS was $0.15, a 6.3% shortfall from the $0.16 consensus estimate. Revenue came in at $410.3 million, slightly above Wall Street's forecast of $405.8 million, representing a 1.1% beat. This figure marks a 13.0% increase from the $361.7 million recorded in Q2 2026.
Revenue Performance
The bulk of the revenue lift stemmed from the subscription services segment, which generated $266.1 million for the quarter, up 11.6% year‑over‑year. That growth signals continued adoption of UiPath's automation platform on a recurring basis, though the expansion pace remains in the low double‑digit range. Adjusted net income reached $80.9 million, indicating the firm can stay profitable while funding growth initiatives. The earnings miss appears tied more to top‑line dynamics than to any underlying operational weakness, as the modest revenue beat was insufficient to offset conservative expense expectations.
Key Financial Metrics
Annual recurring revenue (ARR) stood at $1.938 billion for the quarter, offering a snapshot of UiPath's contracted revenue base—a critical metric for a software infrastructure provider where predictable cash flow underpins valuation multiples. The 13.0% year‑over‑year revenue rise suggests the company is preserving momentum in an increasingly competitive robotic process automation market, even as growth rates have moderated from earlier, faster periods.
Forward Outlook
Management projected next‑quarter revenue in a range of $440.0 million to $445.0 million, implying sequential growth from the $410.3 million reported in Q2. At the midpoint of $442.5 million, the outlook signals meaningful acceleration and reflects confidence that the back half of the fiscal year will be stronger. Investors will scrutinize this guidance for signs that enterprise automation spending stays resilient amid broader macroeconomic uncertainty.
Analyst Sentiment
Wall Street's consensus remains cautious, tallying seven buy ratings, eighteen hold ratings, and one sell rating. The predominance of hold recommendations underscores analyst uncertainty about UiPath's capacity to re‑accelerate growth while preserving profitability in a maturing market. The stock fell 13.9% to $15.69 in morning trade on Friday.
Conclusion
UiPath delivered a mixed Q2 2027 report, beating revenue expectations but missing EPS forecasts. Subscription‑based revenue continued to climb, and the company posted adjusted net income, showing profitability despite ongoing investment. Forward guidance points to stronger performance in the upcoming quarter, yet the cautious stance among analysts highlights lingering doubts about the firm’s growth trajectory in a competitive automation landscape.
Source: news.alphastreet.com · 2026-09-04